
1. Introduction: The Growth-Variance Dilemma in Quantitative Staking
In quantitative gambling and systematic sports trading, bankroll management is frequently treated as an afterthought—a secondary clerical detail subservient to predictive modeling and edge discovery. This perspective is a fatal mathematical misconception. An econometric model possessing a verified, statistically robust +5% edge against closing line consensus can effortlessly drive a bettor into bankruptcy if coupled with an inefficient or hyper-aggressive staking algorithm. Capital allocation dictates whether an asymptotic edge translates into compounding wealth or inevitable ruin.
In 1956, Bell Laboratories physicist John Larry Kelly Jr. published "A New Interpretation of Information Rate", demonstrating that allocating capital in proportion to edge divided by odds maximizes the expected value of the logarithm of terminal wealth: . In pure information theory and frictionless gambling environments with precisely known probabilities, Full Kelly staking is mathematically unbeatable in the infinite horizon. It guarantees faster capital growth than any other staking strategy with probability 1 as the number of trials .
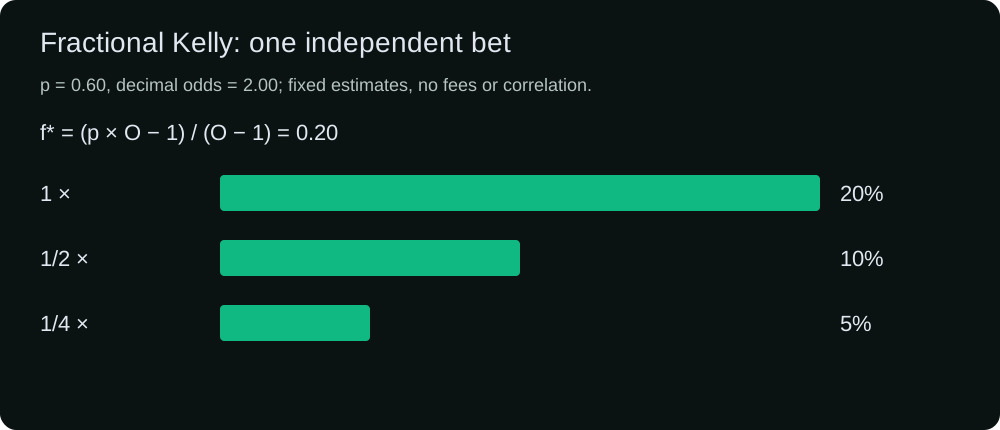
Yet, in real-world sports wagering, professional syndicates and quantitative funds almost never deploy Full Kelly (). Instead, institutional capital universally converges on Fractional Kelly variants—predominantly Half Kelly () and Quarter Kelly ().
The exact benchmark is expected log growth under a specified binary model with fixed, known win probability and odds. Fractional Kelly sets the stake to a chosen multiple of the exact optimum. It changes the allocation, without verifying the probability estimate or guaranteeing a realised profit.
For one-bet simple returns, multiplying the fraction by multiplies standard deviation by and variance by . Thus Half Kelly gives half the standard deviation and one quarter of that variance; Quarter gives one quarter and one sixteenth. These exact payoff identities do not make log-return variance exactly quadratic or determine peak drawdown over a sequence. Reduced exposure can still produce deep drawdowns, as the finite simulation later in this article demonstrates.
This technical monograph examines the mathematical mechanics governing Fractional Kelly staking. We provide formal analytical derivations of the growth and variance functions, prove the parabolic decay of volatility drag, solve the drawdown boundary distribution, analyze parameter estimation errors (), and present empirical results from a 1,000-trial Monte Carlo simulation.
2. Mathematical Mechanics: Deriving the Growth Rate Function
Consider a repeated wagering game where a bettor wagers a fixed fraction of their current bankroll on a proposition offering decimal odds (net decimal return ). The true win probability is , and the probability of loss is . The bettor possesses a positive expected value: .
The Logarithmic Wealth Evolution
If the bettor places independent wagers, of which win and lose, the terminal wealth starting from initial capital is governed by the multiplicative process:
Where with probability , and with probability . Taking the natural logarithm of wealth normalized by initial capital per wager yields the average exponential growth rate :
By the Strong Law of Large Numbers, as , the sample proportions converge almost surely to their theoretical probabilities: and . The expected growth rate function is therefore defined as:
The Optimal Full Kelly Stake ()
To find the fraction that maximizes long-term geometric compounding, we take the first derivative of with respect to and set it to zero:
Solving for yields the classic Kelly Criterion formula:
Checking the second-order derivative confirms strict concavity across the domain :
A concrete check shows the limit of the approximation. With and , exact Kelly is . Half Kelly captures about 75.6575% of the exact maximum log growth and Quarter about 44.5350%. At twice Kelly, growth is still positive in this example. A negative-growth boundary must be found from the exact function, rather than assumed to be twice the optimum.
3. Volatility Drag and the Fractional Trade-Off
The exact benchmark is expected log growth under a specified binary model with fixed, known win probability and odds. Fractional Kelly sets the stake to a chosen multiple of the exact optimum. It changes the allocation, without verifying the probability estimate or guaranteeing a realised profit.
The familiar 75% Half Kelly and 43.75% Quarter Kelly growth ratios come from a quadratic approximation. The Taylor second moment is , not just the variance. Replacing it with variance requires the squared mean to be negligible. The quadratic optimum below is not generally the exact binary Kelly fraction. The table illustrates this approximation; it does not supply universal ratios for arbitrary odds, edges or horizons.
| Kelly Fraction () | Formula | Expected Growth Captured | Variance Reduction | Growth-to-Variance Efficiency Ratio |
|---|---|---|---|---|
| Full Kelly () | 100.0% | 0.0% (Baseline) | 1.00 | |
| Three-Quarter Kelly () | 93.75% | 43.75% Reduction | 1.67 | |
| Half Kelly () | 75.00% | 75.00% Reduction | 3.00 | |
| Quarter Kelly () | 43.75% | 93.75% Reduction | 7.00 | |
| Eighth Kelly () | 23.44% | 98.44% Reduction | 15.00 |
For one-bet simple returns, multiplying the fraction by multiplies standard deviation by and variance by . Thus Half Kelly gives half the standard deviation and one quarter of that variance; Quarter gives one quarter and one sixteenth. These exact payoff identities do not make log-return variance exactly quadratic or determine peak drawdown over a sequence. Reduced exposure can still produce deep drawdowns, as the finite simulation later in this article demonstrates.
A concrete check shows the limit of the approximation. With and , exact Kelly is . Half Kelly captures about 75.6575% of the exact maximum log growth and Quarter about 44.5350%. At twice Kelly, growth is still positive in this example. A negative-growth boundary must be found from the exact function, rather than assumed to be twice the optimum.
4. Drawdown Probability Distributions & Duration
The following table is a continuous diffusion illustration for ever touching a fixed fraction of initial wealth, with no upper stopping target and an unlimited horizon. It is not the chance of a drawdown from a running peak or the chance before doubling the bank. In the formula, is log-wealth drift and its variance rate. Positive drift is required. The fractional exponent uses the small-edge, small-stake approximation; discrete bets can overshoot the barrier.
| Fixed initial-bank loss fraction | Full Kelly () | Half Kelly () | Quarter Kelly () |
|---|---|---|---|
The displayed 50%, 12.5% and 0.78% figures for losing half the initial bank belong to this approximation and its unlimited horizon. They are not exact universal Full/Half/Quarter Kelly probabilities. A finite experiment must measure its chosen event directly. Recovery arithmetic is separate: a 50% loss needs a 100% gain to recover; a 75% loss needs 300%. These identities do not determine recovery time or the share of time spent below a prior peak.
5. Parameter Uncertainty & Model Estimation Errors
The model uses an estimated probability, while exact Kelly theory assumes a known probability. If the estimate is too high, even a fraction of the estimated optimum can exceed the true optimum. The test is the exact expected log growth under the plausible true probability, not a claim that Half or Quarter Kelly absorbs a fixed percentage of estimation error. Lowering the fraction reduces exposure but does not validate the estimated edge.
With known model inputs, strict concavity makes expected log growth decrease after the optimum. The condition defines negative asymptotic log growth under independent stationary bets. At the boundary , zero expected log growth is not a promise of unchanged wealth. A fraction below the model optimum can also lose money on a finite horizon. Model error changes the true optimum and the zero-growth root; a fixed fraction does not provide universal protection.
A concrete check shows the limit of the approximation. With and , exact Kelly is . Half Kelly captures about 75.6575% of the exact maximum log growth and Quarter about 44.5350%. At twice Kelly, growth is still positive in this example. A negative-growth boundary must be found from the exact function, rather than assumed to be twice the optimum.
6. Monte Carlo Simulation: Empirical Trajectory Analysis
This illustrative experiment uses 1,000 paths of 1,000 independent bets, starting at $10,000, odds 2.05 and fixed win probability 0.52. Full Kelly is 6.285714%, Half 3.142857% and Quarter 1.571429% of current wealth. NumPy seed 42 is reset once before the strategy loop, whose order is Full, Half, Quarter. Each strategy then consumes a different sequence from that generator. The Python example below defines the experiment; these figures do not estimate a real betting strategy.
| Metric over 1,000 bets | Full Kelly | Half Kelly | Quarter Kelly |
|---|---|---|---|
| Mean terminal wealth | $598,494.92 | $84,592.82 | $27,494.68 |
| Median terminal wealth | $79,529.84 | $50,504.46 | $24,774.59 |
| Average maximum drawdown from running peak | 80.98% | 52.47% | 30.56% |
| Largest observed drawdown from running peak | 99.73% | 90.88% | 68.53% |
| Ending below initial bank | 15.90% | 5.00% | 3.80% |
In this run Full Kelly has the highest mean and median terminal wealth, alongside the deepest drawdowns. Half and Quarter reduce both simulated growth and drawdown severity. The mean is sensitive to a small number of large terminal values. Seed, horizon, assumed probabilities and staking rules determine these results; the ordering is not a universal guarantee. Drawdown includes the initial bank as the first running peak.
7. Practical Staking Protocol: Rules for Systematic Execution
An execution policy can choose a Kelly fraction, market-specific limits and an aggregate exposure budget. The following settings illustrate those separate decisions; they are not universal professional standards.
Rule 1: Choose a Fraction for a Defined Risk Objective
Quarter Kelly (), Three-Eighths Kelly () and Half Kelly () are possible policy choices. None is an optimal default for every sports market. Choose a fraction against probability uncertainty and a specified loss or drawdown event. Positive CLV alone, or any fixed count of historical prices, does not validate that choice.
Rule 2: Dynamic Liquidity & Edge Haircuts
A policy may use smaller fractions where estimates are less reliable. The following matrix is a chosen example, with no claim about typical market edges, operator limits or restriction thresholds:
- Scenario A, lower assessed uncertainty: A chosen allocation of Kelly. Validate the probability model and executable capacity for the specific market.
- Scenario B, intermediate assessed uncertainty: A chosen allocation of Kelly. Its suitability depends on the selected risk objective, not a universal league or limit tier.
- Scenario C, higher assessed uncertainty: A chosen allocation of Kelly. Smaller exposure does not turn an unvalidated edge into a profitable strategy.
Rule 3: Simultaneous Bet De-risking
Concurrent bets share one bankroll. Their scalar Kelly fractions need not sum to a feasible or optimal allocation; the total depends on the individual inputs and dependence. Use a joint-state optimization or a stated aggregate policy cap. A cap such as is a chosen exposure limit, not a universal bound on loss or drawdown.
8. Python Simulation Code: Replicating the Trajectories
The following self-contained Python script allows analysts to simulate and verify the growth and drawdown profiles across Full, Half, and Quarter Kelly staking:
import numpy as np

def simulate_fractional_kelly(
    num_simulations=1000,
    num_bets=1000,
    decimal_odds=2.05,
    win_prob=0.52,
    initial_bankroll=10000.0,
    fractions=[1.0, 0.5, 0.25]
):
    b = decimal_odds - 1.0
    full_kelly = (win_prob * b - (1 - win_prob)) / b

    results = {}

    for k in fractions:
        stake_f = k * full_kelly
        terminal_wealths = []
        max_drawdowns = []

        for _ in range(num_simulations):
            # Generate random outcomes
            wins = np.random.binomial(1, win_prob, num_bets)
            bankroll = initial_bankroll
            peak = initial_bankroll
            max_dd = 0.0

            for win in wins:
                stake = bankroll * stake_f
                if win:
                    bankroll += stake * b
                else:
                    bankroll -= stake

                if bankroll > peak:
                    peak = bankroll
                dd = (peak - bankroll) / peak
                if dd > max_dd:
                    max_dd = dd

                if bankroll <= 0:
                    break

            terminal_wealths.append(bankroll)
            max_drawdowns.append(max_dd)

        results[f"{k}x Kelly"] = {
            "mean_wealth": np.mean(terminal_wealths),
            "median_wealth": np.median(terminal_wealths),
            "avg_max_dd": np.mean(max_drawdowns),
            "worst_dd": np.max(max_drawdowns),
            "prob_loss": np.mean(np.array(terminal_wealths) < initial_bankroll)
        }

    return results

if __name__ == "__main__":
    import json
    np.random.seed(42)
    result = simulate_fractional_kelly()
    print(json.dumps(result, indent=2))
9. Conclusion: The Quantitative Consensus
The exact benchmark is expected log growth under a specified binary model with fixed, known win probability and odds. Fractional Kelly sets the stake to a chosen multiple of the exact optimum. It changes the allocation, without verifying the probability estimate or guaranteeing a realised profit.
The model uses an estimated probability, while exact Kelly theory assumes a known probability. If the estimate is too high, even a fraction of the estimated optimum can exceed the true optimum. The test is the exact expected log growth under the plausible true probability, not a claim that Half or Quarter Kelly absorbs a fixed percentage of estimation error. Lowering the fraction reduces exposure but does not validate the estimated edge.

