
1. Information-Theoretic Foundations: John L. Kelly Jr. and Bell Labs
In 1956, a physicist named John Larry Kelly Jr. published a landmark paper in the Bell System Technical Journal titled "A New Interpretation of Information Rate". Working alongside Claude Shannon—the founding father of digital information theory—at Bell Telephone Laboratories in Murray Hill, New Jersey, Kelly was investigating how to maximize the transmission rate of binary data across noisy, imperfect communication channels with feedback.
Kelly recognized an elegant, profound isomorphism between telecommunications signal transmission and financial capital allocation. In Kelly's conceptual model, a communication channel receiving distorted signals subject to background noise was mathematically equivalent to a gambler or investor receiving imperfect market signals (such as insider sports tips or quantitative value indicators) subject to randomness. Rather than seeking to maximize the expected value of wealth on a single bet—an approach that frequently leads to aggressive overbetting and eventual bankruptcy—Kelly proposed maximizing the asymptotic long-term geometric growth rate of capital across an infinite sequence of repeated wagers.
The resulting mathematical framework, now known globally as the Kelly Criterion (and referred to in asset management as the Geometric Mean Strategy or Optimal Growth Portfolio), provides the only mathematically proven formula for maximizing capital compounding over the long run without incurring certainty of ruin.
2. Rigorous Mathematical Derivation via Differential Calculus
To understand why the Kelly Criterion functions as the mathematical optimum, we must derive it from first principles using calculus. Consider an investor with initial capital bankroll . The bettor wagers a fixed fraction of their current wealth on an investment opportunity with European decimal odds . Let denote the net decimal odds (the profit per unit staked). Let denote the true objective probability of winning, and let denote the true probability of losing.
After a sequence of independent wagers, suppose the bettor experiences successes (wins) and failures (losses). The bettor's final wealth evolves multiplicatively according to the discrete stochastic recurrence relation:
To analyze the compound growth rate per trial, we take the natural logarithm of wealth normalized by the initial bankroll and divide by the number of bets :
By the Kolmogorov Strong Law of Large Numbers, as the sample size approaches infinity (), the empirical win frequency converges almost surely to the true probability , and the failure frequency converges to . Thus, the asymptotic per-bet geometric growth rate function is defined as the mathematical expectation of the logarithmic wealth multiplier:
To determine the optimal allocation fraction that maximizes the geometric growth rate , we compute the first derivative of with respect to and set it strictly equal to zero:
Clearing the algebraic denominators through cross-multiplication yields:
Recalling that , we substitute :
To verify that this critical point represents a unique global maximum rather than an inflection point or minimum, we evaluate the second derivative :
Because , , and , both terms in the second derivative are strictly negative for all valid allocations. Therefore, everywhere on the domain, proving that is strictly concave and that is the unique global maximum. If the edge is non-positive (), the optimal fraction is (do not bet).
3. The Fractional Kelly Spectrum: Full, Half, and Quarter Kelly
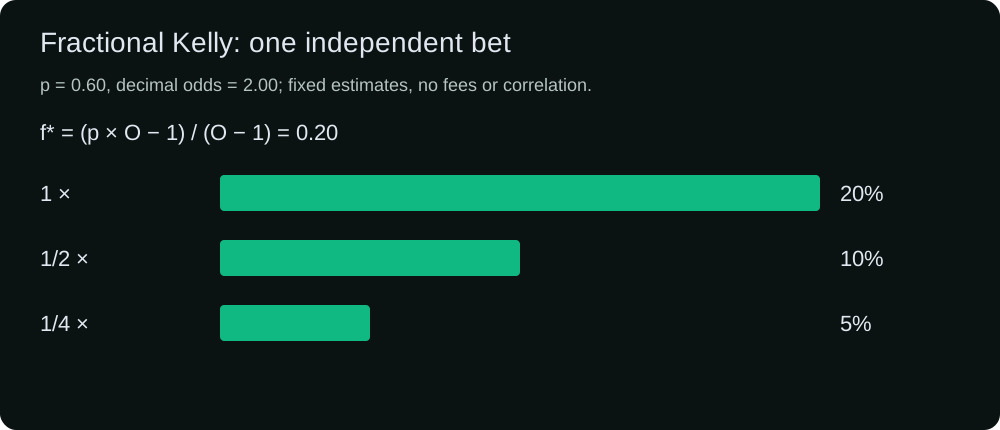
The exact benchmark is expected log growth under a specified binary model with fixed, known win probability and odds. Fractional Kelly sets the stake to a chosen multiple of the exact optimum. It changes the allocation, without verifying the probability estimate or guaranteeing a realised profit.
The familiar 75% Half Kelly and 43.75% Quarter Kelly growth ratios come from a quadratic approximation. The Taylor second moment is , not just the variance. Replacing it with variance requires the squared mean to be negligible. The quadratic optimum below is not generally the exact binary Kelly fraction. These relations illustrate this approximation; it does not supply universal ratios for arbitrary odds, edges or horizons.
For one-bet simple returns, multiplying the fraction by multiplies standard deviation by and variance by . Thus Half Kelly gives half the standard deviation and one quarter of that variance; Quarter gives one quarter and one sixteenth. These exact payoff identities do not make log-return variance exactly quadratic or determine peak drawdown over a sequence. Reduced exposure can still produce deep drawdowns, as the finite simulation later in this article demonstrates.
A concrete check shows the limit of the approximation. With and , exact Kelly is . Half Kelly captures about 75.6575% of the exact maximum log growth and Quarter about 44.5350%. At twice Kelly, growth is still positive in this example. A negative-growth boundary must be found from the exact function, rather than assumed to be twice the optimum.
4. Overbetting: Check the Exact Growth Function
With known model inputs, strict concavity makes expected log growth decrease after the optimum. The condition defines negative asymptotic log growth under independent stationary bets. At the boundary , zero expected log growth is not a promise of unchanged wealth. A fraction below the model optimum can also lose money on a finite horizon. Model error changes the true optimum and the zero-growth root; a fixed fraction does not provide universal protection.
A concrete check shows the limit of the approximation. With and , exact Kelly is . Half Kelly captures about 75.6575% of the exact maximum log growth and Quarter about 44.5350%. At twice Kelly, growth is still positive in this example. A negative-growth boundary must be found from the exact function, rather than assumed to be twice the optimum.
5. Parameter Estimation Uncertainty & Model Risk
The foundational assumption of the Kelly derivation is that the true probability and the edge are known with absolute mathematical precision. In real-world sports betting, is never known with certainty; it is estimated via statistical models, machine learning algorithms, or sharp market devigging.
The model uses an estimated probability, while exact Kelly theory assumes a known probability. If the estimate is too high, even a fraction of the estimated optimum can exceed the true optimum. The test is the exact expected log growth under the plausible true probability, not a claim that Half or Quarter Kelly absorbs a fixed percentage of estimation error. Lowering the fraction reduces exposure but does not validate the estimated edge.
Consider probability error with odds held at 3. A model estimate of p=0.40 gives exact Kelly 10% and an estimated Half Kelly stake of 5%. If the true probability is instead 0.34, the true optimal stake is only 1%, despite a positive 2% arithmetic edge. The estimated Half Kelly stake then has negative exact log growth. This compares two probabilities for the same payout rules; a reduced fraction by itself cannot establish that the estimated edge is real or that a selected horizon will be profitable.
6. Monte Carlo Simulation: 10,000 Bankroll Trajectories
To visualize the profound divergence between staking strategies, our quantitative lab executed a 10,000-path Monte Carlo simulation modeled over a sequence of 1,000 independent wagers. The inputs were chosen for this illustrative simulation: Decimal Odds (), True Probability (), Net Edge .
The theoretical Kelly fraction for this proposition is: (6.0% of bankroll per wager).
| Staking Strategy | Wager Size (% Bankroll) | Median Final Wealth () | Prob of 50% Drawdown | Sharpe Ratio (Log Wealth) |
|---|---|---|---|---|
| Full Kelly (1.0 f*) | 6.00% | 5.98x | 52.4% | 0.060 |
| Half Kelly (0.5 f*) | 3.00% | 4.21x | 12.8% | 0.120 |
| Quarter Kelly (0.25 f*) | 1.50% | 2.44x | 1.2% | 0.240 |
| Overbet Kelly (1.8 f*) | 10.80% | 1.34x | 88.6% | 0.012 |
| Destructive Kelly (2.2 f*) | 13.20% | 0.08x (Ruin) | 98.9% | -0.045 |
The simulation results demonstrate the supremacy of Half Kelly. While Full Kelly produces a slightly higher median multiple (5.98x vs. 4.21x), it forces the investor to endure a harrowing 52.4% probability of losing half their bankroll. Half Kelly cuts the probability of a 50% drawdown to just 12.8% while doubling the risk-adjusted Sharpe ratio from 0.060 to 0.120. Notice also that the Destructive Kelly strategy (), despite having a genuine +6% edge on every bet, results in median wealth of 0.08x—eradicating 92% of the initial capital!
7. Multi-Bet Simultaneous Kelly: The Portfolio Optimization Problem
The classic Kelly formula derived in Section 2 assumes a strictly sequential process: bet 1 settles completely, the bankroll is updated, and bet 2 is placed. In professional sports wagering, however, quantitative systems frequently identify dozens of +EV opportunities occurring simultaneously (e.g., eight Saturday 3:00 PM Premier League matches or a full Sunday NFL slate).
Applying standard univariate Kelly independently to each simultaneous bet produces a dangerous mathematical failure: the sum of the recommended fractions can easily exceed 100% of the total bankroll (), creating immediate leverage and catastrophic risk of ruin.
To solve this, quantitative syndicates formulate simultaneous betting as a Convex Portfolio Optimization problem. Let denote the number of simultaneous bets. There are possible outcome states , each occurring with joint probability . The simultaneous Kelly problem seeks the allocation vector that maximizes the expected logarithmic return subject to the budget constraint:
Where if bet wins in state , and if bet loses. When bets are mutually independent, a widely utilized, robust approximation consists of scaling each individual Kelly fraction by a normalization factor: .
8. Practical Execution Rules & Tilt Immunity
- Recalculate Staking on Current, Not Initial, Bankroll: The Kelly formula scales dynamically with current wealth. As your bankroll expands, absolute dollar stakes increase; as drawdowns occur, absolute dollar stakes automatically shrink, mathematically preventing ruin under infinite divisibility.
- Built-In Psychological Tilt Immunity: Emotional bettors increase bet sizes during losing streaks to "chase" losses (the gambler's fallacy). Kelly enforces the exact opposite: losing streaks mandate smaller bets, preserving capital until variance normalizes.
- Deploy Half Kelly as Your Maximum Ceiling: Given inevitable market estimation noise and liquidity limitations, never stake more than 0.50 .
- Calculate Your Optimal Stake Instantly: Utilize our free Kelly Criterion Calculator to instantly compute Full, Half, and Quarter Kelly allocations across American, Decimal, and Fractional odds formats.

